90 Day Business Tune-Up

Memorial Day Weekend is over and summer is here—-yay! The fourth quarter, which has the most revenue potential for most Freelance and other business entities, will arrive at the close of this short, sweet season and whether it brings you a feast or something less than, you’d better be ready. There’s a lot to prepare for this year.

Inflation has been eating your profits for at least two years. The shakeup that followed the recent collapse of three big banks still lingers and talk of recession refuses to subside. So maybe it’s time to take some defensive action to insulate your enterprise against the turbulence? Ya think?

Then again, you may have reason to feel optimistic. Are you one who anticipates a potentially robust fourth quarter? That happy thought may inspire you to consider scaling your operation, maybe hiring one or more part-time or even full-time employees, to ensure that your organization will seamlessly meet the increased demand for your products and services.

In either scenario, you’ll have some planning to do and it makes sense to start the process now and guess what? You can make a few smart moves that will give your business a summertime tune-up that will start showing the results you want in just 90 days! Analyzing key performance index metrics, numbers that reveal what’s really going on in your business, is Step One. You’ll want to verify the customers who bring you the most business, the average dollar amount of invoices, the average length of your sales cycle and the average number of days it takes to collect receivables, for example. That and other KPIs will help you decide what should be done to capitalize on your advantages, minimize potential obstacles and give some wiggle room when it’s needed.

SWOT Analysis

Objectively evaluating your business on a monthly or at least quarterly basis is always time well spent, regardless of the economic conditions you face. Since the 1970s, the SWOT Analysis has enabled business owners and leaders to account for the Strengths, Weaknesses, Opportunities and Threats that a business should focus on and manage. FYI, there are many free online tools that make it faster and easier to conduct a credible SWOT Analysis, ensuring that you evaluate all aspects of your business and help you consider goals and next steps.

Taking a peek at two or three major competitors can also unearth useful information and may even help you recognize previously undiscovered opportunities to pursue or other potential advantages to explore. Look for what can help your business stand out, including product or service add-ons and upgrades, customer loyalty rewards and customer experience and after-sale support.

Once the SWOT has been completed, identify what can be implemented in the short-term and develop strategies that include action plans and a timetable to keep you on schedule and drive results. Other areas that may benefit from scrutiny and are known to produce tangible results quickly are below.

Cash-flow

Insufficient cash-flow makes it difficult to manage your accounts payable and other fixed expenses and can result in late fees. Two strategies that you can institute immediately are known to improve your business cash-flow— 1.) speed up collection of accounts receivable, usually by timely invoicing and 2.) control spending.

Re: invoicing, time tracking software often has invoicing capability and it’s a timesaver for B2B service providers. Alternatively, you can develop the practice of creating a draft invoice when you send a contract to customers. The services you provide will be described and will be the basis of your invoices. Mostly, you’ll only need to add the time spent on the tasks.

Coaxing customers to pay on time may also mean that you need to broaden your company’s payment systems. Accepting two or three payment formats (e.g., mobile and online in addition to checks) could shorten the average number of days it takes to collect outstanding receivables. In addition to meeting customer expectations and helping to increase sales conversion, digital payments also mean money is deposited to your account within 48 hours.

Re: spending, examine your budget and look for what can be reduced or eliminated. For example, have you been a user of premium services and if so, are the upgrades meaningful? Also, you might consider renegotiating your contracts with suppliers, asking for a lower credit card interest rate if you always pay on time and reduce any discretionary spending.

Finally, money saved allows you to build a nice cash reserve, oh happy day! That means you’ll face the most favorable conditions should you look to obtain a line of credit that provides additional cash reserve. With a line of credit, you can draw from it on an as-needed basis but only have to repay what you actually borrowed.

Pricing

We all know that prices are rising and this gives you “permission” to raise yours—-maybe by 10% -20%? Your customers probably won’t complain, unless they are especially price sensitive. Consumers don’t stop purchasing when prices increase—-they simply adapt to what’s within their budget.

Consider designing a premium and a budget version of your services and add two new price points to the mix. Consumer behavior surveys have demonstrated that shoppers of B2B and B2C products and services appreciate the options of multiple price points. It’s highly unlikely that the majority of your buyers will gravitate to the lower price and in fact, if you design your premium services to reflect what buyers value most, a majority will probably choose to pay the higher price in order to obtain what’s important to them.

Customer experience and retention

If business slows down, it’s imperative that you step up your customer retention activities. Keeping a customer is always less expensive than acquiring a new one, so do whatever possible to persuade customers to keep doing business with you.

Prioritize customer satisfaction. Along with providing high-quality products and services, attentive customer service and beneficial after-sale support will result in significant improvement in customer satisfaction. Furthermore, everything from a website that navigates intuitively, to quick follow-up on questions asked on social media will positively impact the customer experience and the good reviews, repeat business and referrals that every business needs.

Get free advice

I’m honored that you read my blog (thank you!) but there are other sources you can explore and they’ll have information and advice well beyond what I offer. Small Business Development Centers and SCORE, both affiliated with the Small Business Association, offer free technical assistance and resources to owners of businesses of every size and what you learn can make a real difference. .https://www.sba.gov/about-sba/sba-locations/headquarters-offices/office-small-business-development-centers

Your local chamber of commerce or neighborhood business association will charge a (reasonable) annual dues plus a per event ticket price, but you’ll get a good ROI. There will be at least a few events that justify the money invested and you’ll get to meet fellow business owners and Freelancer peers. You might event meet your next client.

Finally, remember that the professionals you hire to provide business support services—your banker, accountant, bookkeeper, HR or IT specialist— also have expertise in addition to the specific service that convinced you to work with them. I’m sure that within their spectrum of expertise, they’ll be delighted to share valuable insights and maybe even help you to recognize new opportunities.

Thanks for reading,

Kim

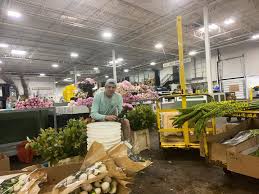
Image: Kelley Wholesale Florist at The New England Flower Exchange in Chelsea, MA.

Navigating Difficult Business Conditions

As business conditions in the US and the world continue to deteriorate, it becomes increasingly important for business owners to devise and implement strategies to shield their entity as much as possible from the economic fallout. When the going gets tough, the smart start planning. In general, encouraging sales revenue and figuring out which expenses can be trimmed are primary ingredients of your business survival recipe. There are other actions you are also advised to consider.

Review financials

Reviewing and interpreting your financial data enables you to make wise decisions that will protect your company. To understand which protective strategies may be sensible and possible for your entity, the planning process begins by first consulting your financial data. Refer to the overview of the big three financial statements in the April 18 post. Trust the story the data tells you and plan accordingly.

The Cash–flow Statement shows the ebb and flow of money through your business and allows you to predict when the most cash will be available and when cash will be at a low point. The tidal flow of money is critical to surviving a business slowdown. The Income (Profit & Loss) Statement reveals which products, services and other activities are most lucrative and you’ll want that information, too, as you construct the plan. On the Balance Sheet, you’ll find company assets, liabilities and outstanding debts or loans. Now you can determine where the business stands financially and how the possibility of decreased revenue could affect you. Your survival plan will start to take shape.

Study the previous 24-36 months of business performance history and use that information to project 24-36 months into a future that will be colored by a degree of turbulence. Each month, monitor relevant KPI (key performance indicator) values that reflect income and expenses, including:

  • top line revenues (gross sales)
  • accounts receivable (outstanding invoices)
  • accounts payable (bills owed by the business)
  • payroll (W2 and 1099NEC)
  • rent
  • utilities
  • software subscriptions
  • taxes

It is imperative that you’ll be able to cover accounts payable obligations and payroll for employees and/or Freelance outsourced help. You do that by doing whatever possible to ensure that accounts receivable are paid on schedule. Invoice on time and include a line that states payment is due upon its receipt. In reality, an invoice that is 45 or fewer days old isn’t past due. However it’s always in your interest, particularly when business is slow, to collect receivables quickly, to promote the timely payment of what’s payable.

Create action plan

Planning for an expected economic slowdown is how to prepare your business for survival. Don’t wait until you’re underwater. To power difficult a difficult business climate, business owners are advised to take a view from 30,000 feet look at the operation. See the suggestions below for tried-and-true recommendations that could help you save the day. If you have the money, it’s also a very smart idea to create an emergency fund and purchase business interruption insurance, to cushion the blow if disaster strikes. Who could have predicted either the events of September 11, 2001, or the arrival of the coronavirus and the subsequent months-long shutdown?

Trim operating expenses

Trimming operating expenses is an obvious and effective way to soften the impact of a sluggish economy. Examine your budget and reduce or eliminate paying for what you don’t need. Also, pick up the phone and attempt to negotiate lower credit card and/ or loan interest payments, cell phone rate and more favorable vendor contract terms (if your payment record is good). Marketing automation and other software as a service subscriptions might also be lowered by a modest amount each month.

Business travel, maintaining membership in certain business or professional organizations and attending certain conferences and trade shows may be expenses that you should continue, if possible, if the ROI is good. Don’t bite your nose off to spite your face. If you can cut even $50/ month your accounts payable tab, it’s a victory.

 Prioritize customer retention

It’s been convincingly demonstrated that it costs 5x more of your valuable time and money to bring in a new client than it does to retain the client you already have. Your relationship with existing clients will be an important asset during turbulent times. Keep them coming back by not only offering the products and services that deliver the solutions they need, but also by providing the customer experience they value.

Invite feedback, sometimes by finding opportunities where conversation with your clients can take place or by sending out a quick survey, maybe with your next invoice, so that you can learn how clients feel about doing business with your organization. Client feedback may alert you to problems that need your attention, information that is crucial. Inviting feedback also demonstrates that customer satisfaction is a priority at your company and it further enhances the customer experience.

Focus on best-sellers

In an economic downturn, promoting your best-selling products and services is a prudent strategy for both attracting new clients and maintaining current clients. Let the top line revenue on your P&L be your guide. Furthermore, support your top line by ramping up your customer retention strategy (or create one). Next, evaluate and optimize the customer experience your company provides as well, including after-sale support. Make the most of every touch point.

Revamp leadgen marketing

Don’t let tough economic times diminish your brand’s success. Instead, reassess your marketing strategies to stay ahead of the competition. If you’re working with a tighter budget, narrow marketing focus to enhance customer loyalty and encourage retention. Energize social media presence and digital marketing solutions to increase your brand’s visibility. Keep your finger on the pulse of the latest trends in marketing to tap into what’s capturing the attention of your target audience.

If you or a friend are adept at shooting and editing visually-engaging short videos, revitalize your marketing on YouTube (if your A/V skills are good), TikTok, or Instagram. They key is getting creative in your marketing messages to stand apart from competitors. By all means necessary, during the adverse economic conditions (and also when things improve), stay visible, watch your financials, be agile, look viable stay relevant and be cautiously optimistic.

Thanks for reading,

Kim

Image © Susan Doyle (pictured), founder and owner of Go Paddle in County Wexford, Ireland is an avid kayaker, coach, outdoor educator and a paddling ambassador for Canoeing Ireland through the Bridge the Gap program.

Social Media for the B2B Freelancer

As you do your best to navigate through the COVID era, one obvious change has been that life and business are largely conducted on the internet, Step-by-step, especially since Y2K arrived (were you afraid to ride in an elevator on 12/31/1999?), so much of life started moving over to the internet. The coronavirus shutdown of March 2020 acted like a rocket booster and pushed millions of businesses—supermarkets to pharmacies, restaurants to home furnishings stores, classroom instruction from grade school to college level, luxury apparel boutiques to plant stores—to prioritize their online presence. You may have begun to work from home, plunging into video meetings and Slack and other workflow communication tools. This is a permanent inflection point and there can be no going back.

It’s fairly certain that you participated in social media in your personal and/or professional life prior to the COVID era but if you are a Freelancer or other business owner or leader, you recognize that the need for creating a sophisticated social media strategy has been ratcheted up. Officially, your social media presence can no longer be treated as an afterthought. Your chosen platfroms now own a pivotal role in your organization’s sales/marketing funnel, a critical client recruitment tool. Social media is now integral to supporting your brand, often by telling your brand story and building a community of loyal client cheerleaders who enthusiastically sing your praises. Make optimizing sthe use of social media in your organization your first business strategy decision of 2023.

Enhance brand awareness

LinkedIn remains the most popuar platform for those searching for B2B solutions. Complete your regualrly update your profile. When you receive new certificatons, upload them. If becoming (or remaining) a thought leader in your industry is a goal for you, social media provides a path and LinkedIn is considered a trusted source by most. You’ll find this blog post on my LinkedIn profile. If you’ve been a podcast guest or host, post the link, ditto for a webinar.

If you’ll teach a class, deliver a talk, moderate or participate on a panel, post the invitation on your profile. Participate in the still-relevant LinkedIn Groups feature and chat and exchange information with your professional peers. LinkedIn’s new Creator Accelerator Program a 6-week program that shows you engage your audience and grow your target audience. There is an application process involved, Contact the Creator weekly newsletter for more info. Stay up-to-date with your Notifications and receive feedback from followers and those who’ve responded to your content.

Sales/marketing funnel

The benefit of sharing informative content is that you may soon be seen as a trusted surce and expert in your space, making it easier to be seen as a credible resource and not just another salesperson. Social media browsers are known to use their preferred platforms to research products and services. This is a huge opportunity for you to use social media as a platform to add value by sharing informative content. As such, you’ll spend much less effort trying to “convince” target audience members to do business with you once familiarity and trust have been established.

Improve your understanding of what motivates potential buyers in your target audience to turn to social media before posting your content, to ensure that your information aligns with what potential buyers want, and need, to know. In general, a case study or two, your newsletters and your blog posts will answer most questions and demonstrate your organization’s ability to meet client needs.

Leverage the power of client testimonials and give yourself additional credibility by way of a real-time description of the capabilities of your organization. Your approach to delivering the solution, handling of the inevitable obstacles that challenge along the way and your team’s customer service and after-sale support will go a long way in showcasing your venture and building trust.

  • What are aspiring buyers in your category looking for and what do they hope to achieve?
  • What drives potential buyers to use certain keywords, hashtags, or phrases when searching in your category?
  • What products or services are they using now, or previously, to achieve the goal, or attain the solution to resolve the problem now?

Feed your sales/marketing funnel by demonstrating that you and your team can get the job done. Potential buyers will seek for more information and may eventually schedule a video or telephone call to talk things over and get a better sense of you and what it might be like to partner with you and work on the project.

Building community

How does one encourage the engagemet of your customers? Maybe start with a couple of polls and then get a discussion going? Those thriving the most in today’s evolving engagement landscape are able to use their social following and allow users to contribute and interact rather than simply judge and scroll. This can be accomplished in a multitude of ways, including inexpensive swag gift giveaways polls, posting LinkedIn story video or audio testimonials or reviews. If you’re participating in a charity event, video some portion of the proceedings and make that a LinkedIn story, too (you will have already posted it as an event, am I right?)

The key is to execute thoroughly and listen to your community: Simply having a giveaway may create interest, but communicating the rules, perks and actually following through by showing the community how their involvement moves the needle toward something positive is the ideal. This could happen any number of ways, and requires considerable thought from those close to the brand who understand how to best engage its community.

Happy New Year and thanks for joining me,

Kim

Image: Kim Clark. The groom in a wedding party approaches The Park Plaza Hotel in Boston, MA (2019)

How to Thrive in the New Year

Whether your venture is a recent start-up or a mature entity, it is a given that business owners and leaders must continually take steps to spur business health and vitality—in other words, growth = life. Many small businesses don’t make it past their first few years so to increase your chances of success, you have to be strategic from the very beginning. It’s important to direct your energy and resources toward actions known to work. Without a rationable straight-forward plan for growth, your business could struggle to take off and become sustainable. Presented here are five basic growth strategies, one or more which will likely work for your enterprise.

  1. Increase market penetration
  2. Indentify new channels
  3. Introduce market segmentation
  4. Develop partnerships
  5. Prioritize exising customers

Market penetration

This is a fancy way of telling yourself to cultivate a thriving client roster that is populated by a mix of new, lapsed clients who’ve been enticed to return and, best of all, legacy clients you’ve worked hard to keep within the fold. Market penetration is arguably the most critical business strategy of all; Freelancers and small businesses owners and leaders would be wise to employ ongoing tactics to take aim at long-term success with the use of a good market penetration strategy.

The goal is to increase sales within your current market. This can be difficult, as it requires you to beat your competition, but appealing to your current client list is an often successful path to growing sales revenue and profits. Clients do business with those they know and like and they do more business with those they know and trust.

New selling channels

Finding new opportunities to sell your products can be an excellent way for your small business to grow, especially if your current market is highly competitive. The internet has opened up alternative selling opportunities, giving you unexpected and innovative ways to reach out to not only your existing clients but to other markets, too. For example, if your business is online-only, consider opening a pop-up shop, maybe to capture Valentine’s Day or Mother’s Day shoppers. If the strategy is promising, consider devising a way to become a permanent fixture at the pop-up location. See the partnership heading below and consider the possibility of a consignment arragement with a vendor colleague whose products complement yours.

If your small business operates from a physical store, then do the reverse and consider selling certain of your products online to broaden your reach (work with a skilled product photographer who will make your products look their best). B2B service providers can perhaps bring certain of your services online—maybe coaching sessions conducted by way of videoconferencing?

Market segmentation

Here, we have another fancy term for a simple tactic. Freelancers and small business owners often struggle to get traction in large markets because it’s nearly impossible to compete with bigger and better-financed companies. They’ll out-flank you on every metric, from breadth and depth of their product line to the advertising budget. For this reason, you might need to reevaluate your brand’s place within your market and hyper-focus your preferred playing field.

Think niche. Market segmentation involves dividing a broader market into smaller groups based on demographic information or buying habits. Then, you can choose one of these segments for your niche target audience. Marketing to a highly specific group of potential customers is easier than trying to appeal broadly to a massive group.

If you offer more than one product or service, market segmentation also helps you promote different products or services to different consumer groups. Taking this marketing approach will require careful research to discover which market segments are the most likely to buy each of your products or services, so be prepared for a time-intensive process. You can use email surveys, website analytics and purchase histories to find trends in your existing customers’ demographic or behavioral traits. Once you identify the most appropriate market segments for each of your product categories, create more targeted content for potential clients.

Partnerships

Partnering with another small business gives all parties involved access to a wider audience and if all works according to plan, everyone generates more sales and makes more money. However,

You’ve gotta know who you plan to dance with because a disappointing partnership deal can get ugly and steps must be taken to avoid misunderstandings and confusion. Due diligence is imperative when proposing a partnership of some sort. It is critical that you discuss the agreement—- responsibilities of the partners and expectations for outcomes—-in advance and, ideally, in face2face meetings. Then, follow up the agreement with unambiguously written emails. Due diligence is a must- do when proposing a partnership of some sort.

The partner’s products and services should be complementary, never a competitor, to your line, to ensure their client base will have an interest in your products or services. Ideally, a partnership should significantly benefit both business ventures. A partnership can take any form, from selling items on consignment to co-hosting a full or half-day professional development conferenceto sub-contracting a portion of a project where your own expertise would fall short—providing graphic arts or videography services at an event where you are he principle player. services could be an opportunity to tackle a big project by combining your resources, and it can be a chance to connect with another professional who may be able to offer their wisdom or skills. You could work with a partner to develop a new product, or you could host an event that promotes both brands. A consignment sales arrangement is usually low-stress and can be tested quickly and easily to illustrate how partners can work together.

Current clients

One of the most ill-advised yet common strategic missteps that business owners routinely make is prioritizing new client acquisition over developing client retention protocols. Clients with whom you have a history have demonstrated their confidence in your organization and need only a little love from you and your team to secure their loyalty and future business. While there is no doubt that recruiting new customers is an essential business goal, it is in fact customer retention that is the key to business success, as we discussed above in market penetration. Convincing a client to remain (or return) to your business is far easier than convincing a new client to give you a chance. Client retention is the engine that drives sales revenue and profit. Moreover, current and returning clients are your cheerleaders and are a good source of word-of-mouth advertising.

BTW, an email marketing strategy is probably the easiest way to stay in touch with the roster of clients you regularly work with. The right call-to-action will help you persuade clients and other website or social media visitors to surrender an email address in exchange for receiving something (free) that they value, such as an interesting report, informative e-book, revealing case study, or link to a podcast or webinar in which you participated (always provide an opt-out feature).

To your curated list, you may promote your brand and yourself by sending updates about new products or services, talks you’ll give, classes you’ll teach, charity events you’ll join, special pricing deals and other relevant news. Finally, you can as well demonstrate your respect for your clients by periodially conducting (short) surveys to guage their opinions on how you address their needs and what you can do to improve the client experience.

Thanks for reading and Happy New Year. I appreciate your presence and support!

Kim

Image: This is how we do it. Window washers from a family-owned small business in Gresham, OR working for a local small business colleague. © The Oregonian March 21, 2013.

Fix the Flaws in Your Tactical Plan

Look at it this way—if every time you and your team develop goals for your organization all of the goals are achieved every time, take it as a sign that you should be more ambitious. Goals should challenge! Working toward goals should test you and make you grow.

But if the opposite happens and it becomes clear that your strategies and actions are not moving you toward success, you’ll need to stop and discuss. You must understand why things aren’t happening and decide what you can do about it. For sure, a change will have to be made, but how might you figure out what to change?

Today we’ll break down the elements of working toward goals — the actions taken, the strategies, which are pathways, and finally, the goals themselves. Our objective is to recognize what part of the plan is fatal and what is fixable. Spoiler alert–everything is connected. Each component of your plan must support, and be supported by, the other components.

Actions and strategy

It makes sense to start by examining actions—closer to ground level. Every action you or your team takes should be devised to align with and support a specific strategy. All actions should have a purpose that is readily identifiable as a cog in the wheel that carries out a strategy. So if the wheel stops turning, it will not be too difficult to pinpoint the problem and make whatever necessary adjustments.

You may also benefit from rethinking the metrics used to monitor the efficacy and progress of the actions. Are you tracking and measuring the right data? Does the data provide an accurate picture of how your action items contribute to reaching the goal? If not, reevaluate and substitute more meaningful metrics.

Strategies and customer priorities

What matters most is that customer preferences and priorities are tied to and reflected in your strategies. If you’ve analyzed your team’s performance and your actions are on target as regards the plan, then the problem may well lie in the strategy, the wrong path. Perhaps it’s no longer viable?

Or maybe you’ve overlooked other data that indicate customer needs and interests are evolving? If that’s the case, you’ll need to update to ensure that your strategies align with what matters most to customers. You may not need to revise your goals but rather, revise strategies.

Verify the alignment, or lack thereof, between your tactics and strategies. Remember that your actionable tasks are designed to further a certain strategy. It is therefore essential to confirm that you’re using the right tactics to impact the strategy.

SMART Goals

If you’ve taken a cold, hard look at both the strategic and the tactical plans without pinpointing an opportunity for making a timely and productive shift, then it’s time to reconsider your choice of goals.

The problem with your goal may be situational — i.e., what was a valid, realistic goal has lost its luster. The world has turned and now you need to play catch-up and align with the current environment and market. Or it could be that there’s nothing wrong with the goal itself; you just haven’t fully identified, defined and fleshed it out. Reality test your goals by asking yourself the following questions:

SPECIFIC: Specific means “Show a revenue increase of $X and growth in profit of Y% by the end of the current fiscal year,” and not “show an increase in revenue and growth by the end of the fiscal year.”

MEASURABLE: What are the metrics you’ll use to document your progress (and why are they relevant)?

ACHIEVABLE: Is your goal attainable and realistic both in the absolute sense and within the resources—-time, expertise, money—-you can devote to its achievement?

RELEVANT: Does your goal make sense? Does it align with your values and mission of your organization? Does it get your company closer to where you want it to be, in market penetration, referrals and repeat business, revenue earned, or profits made?

TIMELY: Is the time right to pursue and benefit from the attainment of this goal? Also, do you have a clear starting point and metrics targets or deadline date to assess the final result of your initiative?

Thanks for reading,

Kim

Image: ©Winslow Townson, Associated Press. New England Patriots quarterback Tom Brady in the huddle at the December 17, 2017 game against the Steelers at Heinz Field in Pittsburgh, PA

10 Strategies for Surviving a Bear Market

Step right up folks. Welcome to the bear market. Wasn’t this the party you were looking for? Probably not. But the bear market bus has left the station and you have no choice but to hang on for the ride. Get used to it—bear markets are stubborn. The bear market known as the Great Depression technically lasted for 3 years (1929-1932). The Dot.com Bubble bear market lasted 2 years (2000-2002).

However, the negative effects of bear markets—-high unemployment, inflation (higher prices paid for essential items) and downward pressure on business revenue (resulting from lower disposal income that limits discretionary purchases and higher interest rates on business loans)—-usually doubles the real-time negative effects of bear markets on the population.

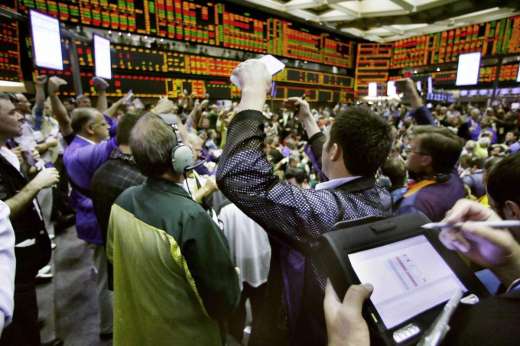
So what is a bear market anyway? Economists declare a bear market when there are sustained declines of 20% or more in (recent) prices of stocks, bonds, mutual funds and commodities across several market indexes and exchanges —Standard & Poor”s (S&P 500), Moody’s, the New York Stock Exchange (Wall Street) , NASDAQ, and the Chicago Mercantile Exchange are among the well-known economic benchmark sources. Bear markets usually occur in tandem with a weak economy.

You may notice that stock and other securities prices demonstrate investor confidence and optimism. The high prices typical of a bull market, polar opposite of the bear market, indicate an expectation that big institutional investors are expecting growth and expansion of the economy. But in a bear market, it’s all about avoiding risk and conserving cash.

So, too, for Freelancers. Pulling back and going on the defense is the smartest bear market strategy. Conserve cash by trimming expenses that do not demonstrably contribute to customer acquisition, customer retention and the customer experience. Manage expenses to preserve your cash-flow. If you are able to save money on a regular basis, so much the better, so that you’ll have funds available to cover business and living expenses if revenues take a serious dip,

Be very cautious about plans to grow, expand, or scale your business and remember that business expansion costs money, a resource that is more expensive to obtain during high-interest bear markets. You can go out of business in a blink if you start drinking from the fire hose and expand too much and too fast.

You can run out of money because you can’t bring in customers fast enough to cover operating expenses. You can also be caught off guard by factors outside of your control—-like a pandemic lockdowns, a boat turned sideways in the Suez Canal, another war or assassination—- that deflates your once/ reasonable sales projections.

Furthermore, customer acquisition and retention are usually more difficult to sustain when disposable income drops and potential customers pull back on spending. Still, with the right strategy you might make money, or at least avoid big losses. Below are actions to help you minimize the bite of the bear.

  1. Open a cash reserve account and aim to deposit 5%-10% of weekly net revenues. If you encounter ether an emergency or an opportunity, you will have waiting for you an interest-free line of credit, so to speak, to carry you through an unexpected cash-flow glitch.
  2. If you sell products rather than services, find back-up supply chain resources so that your shelves will remain stocked even if your usual supplier experiences delays. You must have products to sell when customers want to buy.
  3. Be cautious about plans to expand your venture, unless trustworthy research shows the ROI the time and money required.
  4. Cut excess operating (selling, general & administrative) expenses.
  5. Boost AOV (average order value) by bundling products together to increase sales revenue. Make it attractive to buy from you.
  6. Minimize or eliminate perks —-offsite retreats, meals, travel and the like—- unless you’re spending on customer acquisition or productivity-enhancing skills development.
  7. Raise prices in response to the impact of inflation on the rising cost of goods sold, to maintain profit margins.
  8. Consider investing in long-term opportunities or capital improvements that might now be discounted significantly. Who knows, if the financial prospects are good, maybe you can buy out a competitor who has good market share, but doesn’t have the money to overcome the bear market—/and you do.
  9. Focus marketing in the top three performing channels only and drop those that don’t add much to your sales/ mart pipeline.
  10. Use cash-flow and higher operating margins( (obtained by raising prices) to provide the working capital you need. Remember that the interest you pay on borrowed money from your bank is now higher with rising interest rates.

Thanks for reading,

Kim

Image: © The New York Times The Bear struts his stuff in the Boston Ballet production of The Nutcracker.

How Does Your Garden Grow?

Sales at your business venture have finally taken off and it looks like you’ve created a winner—-fantastic! Because you’re ambitious, you’re already thinking about how to capitalize on your success. You’re looking to grow because sustainable growth is the key to maintaining a thriving businesses. But let’s slow down for a minute and talk about how you might grow your venture? Business growth has different meanings and one or more paths can be taken to achieve it. What you’ll need to successfully grow your business is the right growth strategy.

As always, big decisions demand careful thought and you’d be wise to analyze the relevant business metrics and also the marketplace in which as you operate as you ponder the kind of growth you should pursue for your organization. The path to growing your business must fit your marketplace conditions, be acceptable to target customers and enable the venture to thrive within its competitive landscape.

Researching the state of your industry, local business conditions and your marketplace are among the steps you’ll take to assess growth possibilities for your venture. Analyzing your customer base and documenting the rate of its expansion over, say, the past 12-24 months is an obviously important step you’ll want to take, as is studying the pace of sales revenue. Information and insights you discover will shape the expectations and goals for growth and allow you to build a timeline and budget for your chosen growth strategy.

Your business growth plan should be attuned to specific areas of growth. For example, your research and analysis may lead you to conclude that revamping a couple of your B2B services could be expected to substantially increase sales revenue derived from a niche market that you have the credibility and resources to enter. Or maybe relationships that you’ve developed in another city will allow you to grow your client list / customer base by expanding to establish a beach head there.

In many ways, your primary task is to figure out why the business is successful. What market conditions exist or what competitive advantage have you created that enabled the business to thrive? The answer to that question will help you decide the growth strategy to follow. The following are strategies that you might pursue to grow your venture.

Market penetration strategy

Continuing to sell your current products and services to a greater number of customers and in that way scale up the volume of sales revenue derived from your current market. A market penetration strategy is a product market strategy where you achieve increased dominance in the market in which you currently operate. The company grows by increasing market share.

Market expansion strategy

Entering a new market where you sell current products and services. A market expansion strategy means you’ll plan to sell current products and services to a new customer demographic because you’ve maxxed out growth potential in the company’s current target customers. Being able to successfully follow a market expansion strategies you’ll first confirm that you have actually topped out on sales in the current configuration of your market.

Next, research potentially viable new markets, evaluate your ability to reach customers in that market and create a plan to launch. Brand development and customer acquisition will be key components in a market expansion growth strategy.

Product expansion

Launching a new product or service to sell in your current market. The ability to achieve growth for some businesses requires that the company needs to introduce a new product or service. Product development, that is, the creation of a new product/service, or the enhancement of an existing product/ service, enables the company to attract new customers and as it retains the existing customer groups.

Diversification

Launching new products or services to sell to a new market. Diversification can be a proactive way to avoid the fallout of an economic downturn. By offering different products and services, a company can lessen the negative impact of a recession. Pivot to survive.

For smaller organizations, what is technically known as horizontal diversification is most useful. The company will add new products or services to its current line. The products or services may be new, but they often have a similarity to the original product/ service. The company diversifies its line with a clever tweak that expands in a desirable way the options to the customer. You may add a refinement or some sort of updated (or pared down) option that appeals to shifting customer priorities and preferences.

Acquisition

Buying out or taking a controlling interest in another company. Acquisitions are usually only a viable growth strategy if you have excellent cash flow and a generous line of credit at the bank, or a group of deep-pocket investors available. If you have access to money, growing your business through an acquisition is the way to go. You can reduce competition by acquiring a direct competitors, for example. You can also obtain proprietary technology that confers to you a significant competitive advantage. Market share and customer share increase because you capture a new customer base.

To my American friends I wish a happy 4th of July! To everyone, thanks for reading,

Kim

Photo: © Kim Clark June 11, 2021. The James P. Kelleher Rose Garden in Boston’s Emerald Necklace

Good Questions Are Your Best Sales Strategy

Many factors influence a B2B sale, including egos and power struggles, budget allocation and politics, trending industry fads and the success or failure of what’s been done before. But as you know, Freelancer friend, you can only control what you can control.

To obtain some measure of control you need information, because knowledge is power. To determine whether there is a sale here for you, you’ll need clarification of the factors listed below, which are known to influence B2B sales. Knowing if there was a recent attempt to reach the goal or resolve the problem before you were contacted is also useful intel, as is knowing if the prospect is actively considering another solution (that would be provided by someone else).

  • Define the problem or goal and learn if it’s high priority or urgent
  • Understand what the prospect wants you to do and when it must be completed or delivered
  • Is the prospect talking to a competitor?
  • The decision-maker
  • Estimated budget

The most efficient way to get the backstory on your sale and create for yourself a realistic chance of winning is to ask questions that bring out the answers you need. Phrase the questions in words that feel natural for you. I think what’s listed below will both lead you to more sales and quickly eliminate those who present themselves as interested but are just not that into you.

1. What led you to contact me/ respond to our outreach?

2. Is getting this project done/ product installed an immediate priority? When would you like to see it completed/ made available?

3. Have you been using a solution (i. e., a product or service) that isn’t working? What fell short of your needs?

4. What. are three key outcomes you want to occur when the goal is reached/ problem is resolved?

5. What other options are you currently considering?

6. Which department in your company will be the end users of the product/ or who will be my contact as the service is implemented?

7. What kind of support/ training/ post-sale service would your team like to receive as the solution is being implemented or when the product is purchased?

8. Are you the person who decides the budget for this project and has funding been allocated?

9. Based on what you’ve told me, I think my organization can help you achieve your objectives. I’d like to work with you! What is your decision-making process like?

10. Is there anyone else who might appreciate having a conversation about this solution? Anyone else I might speak with?

Thanks for reading,

Kim

Image: Judy Holliday (standing) has a couple of incisive questions for her husband (Tom Ewell) and the other woman (Jean Hagen) in Adam’s Rib (1949, directed by George Kukor and starring Spencer Tracy and Katharine Hepburn).

Making Sense of Your Data

When you think about it for a minute, you might agree that basically every aspect of your business can benefit from relevant and timely information—-i.e., data. However, your potentially helpful data can leave you with a puzzle to put together, unfamiliar terrain to navigate, before you can make sense of the information and understand the picture it’s trying to show you.

The puzzle pieces that contain your data could be expressed in various formats, e.g., columns of numbers, pie charts, bar graphs, or the written opinions of researchers and thought leaders. Furthermore, the data sources often use different benchmarks and measuring standards and make getting a sense of things sort of a wrestling match.

Analyzing data reminds me of buying produce at Trader Joe’s and Whole Foods. At Trader Joe’s, the bananas are 19 cents each and there are no scales. At Whole Foods, bananas are 49 cents a pound. How can I calculate what I’m paying for the fruit or the other produce that I buy at each market and compare prices?

Data analysts and other experts say that for much of the information we access, tools that cut through the maze and bring focus to the picture, such as identifying patterns and trends for you to consider, are a must. Otherwise, you’ll be unable to fully comprehend the data’s story, unable to make good use of the information and enable it do what you need it to do, which is to support good decision-making. Micrsoft Excel or Power BI, Python, Jupyter and Apache Spark are among the most highly rated data analytics tools.

Among the most common functions that data analysis is called upon to provide insight are:

Marketing teams use data to examine website visits, often by way of Google Analytics and social media stats, by way of services such as BuzzSumo, Sprout Social, or HubSpot. Understanding what’s happening in the company’s marketplace and revealing customer behavior by analyzing Descriptive Analytic data is a typical goal.

Sales teams use data to understand the customer buying journey and learn what motivates a sale, along with revealing customer buying patterns. With access to unlimited online information, prospective customers are better informed about potential purchases than they’ve ever been. B2B sales researchers have documented that prospects are usually 80% of the way through the buying cycle before making contact with a sales team. Customers are in the driver’s seat.

Finance/ Accounting teams have always had access to the reams of data that’s attached to invoices, accounts payable and receivable transactions, sales revenue, inventory counts and other movements of money and resources.

Operations teams are charged with continually reviewing any number of business processes, from how to source or manufacture the products and services that a company sells, to recommending the most optimal methods to connect those products to customers, to ensuring that company offices are equipped with effective HVAC systems. Obtaining data that reveals operational efficiencies and enables business functions to be executed in the easiest, fastest and least costly or risky methods is the eternal goal.


Yet the question has always been, how can anyone—-multinational conglomerate or Freelance solopreneur—-maximize the value of your data?

  • Put data to work Your data is wasted unless you examine it, interpret it and let it guide your actions and decision-making.
  • Sort and analyze Appropriately grouping, categorizing and analyzing your data makes business intelligence tools necessary when working with large amounts of data. Today, data analysis means Artificial Intelligence. AI-powered systems will in mere seconds collect, sort, analyze and make meaningful recommendations for you and your team to review and evaluate. If that’s not enough, your AI tool will ”learn” from the data you feed it and the recommendations it makes to continually refine and improve the outcomes.
  • Strengths into opportunities Let your data show you where you shine. Maybe it’s your amazing referral rate or customer retention rate. Maybe it’s the memorable customer experience that you create or the loyal followers who’ve turned into brand cheerleaders for your company.
  • Prioritize Get clear and pragmatic about goals and objectives the organization would be wise to pursue over the long and short terms. Your customers and their emerging preferences and priorities are certain to influence the strategies and actions that emerge at the head of the line. Let the marketplace guide you.

Thanks for reading,

Kim

Image: © Warner Brothers Pictures. Malcolm McDowell in A Clockwork Orange (1971), directed by Stanley Kubrick 

Moving the Needle on B2B Sales Deals

Selling B2B professional services is no day at the beach, as you’ve probably deduced by now. Getting B2B sales deals across the finish line can be an uphill marathon that leaves you face down on Heartbreak Hill. Unlike your B2C colleagues, you can’t ride the wave of multi-million dollar product launches or other advertising campaigns to convince prospects of the amazing benefits that your product or service delivers.

Moreover, there are no impulse buys in B2B, no equivalent of customers adding candy to their shopping basket while waiting in the check-out line. Your marketing campaigns and sales pitches speak to business goals with a deadline and problems that must be resolved.

On top of that many, if not most, B2B services that Freelancers provide are unlike the various software as a service products that can be easily compared and evaluated, feature by feature. Once a prospect has found you, it’s necessary to pitch your solution in a narrative mix of hard facts and soft skill intangibles that portray you and your capabilities as an effective and trustworthy choice.

In some instances, you may even work to convince a prospect that there actually is a problem to solve, that something can be done in a faster or easier way. As a result, the sales cycle of the typical Freelance consultant is long. So what can you do to keep the pipeline filled and your cash-flow positive now and into 2022? There are some cultural shifts to keep in mind as you consider strategies that you might implement.

The Great Resignation factor

In the early 2000s, I started to notice that important contacts at companies with whom I worked regularly disappeared in about two years. Not good! So much of obtaining repeat business depends on relationships. It costs you money when an ally leaves a prospect’s decision team. You may not know where they’re going next and they usually don’t take you with them by introducing you and your services at their next assignment

This phenomenon is detrimental to the future of your business. The Great Resignation factor (addressed in the September 7, 2021 post) has heightened this trend. Freelancers are advised to include this reality in client pursuit and post-project client retention strategies. You can’t control what will happen, but knowing that a change is brewing gives you the opportunity to ask who will join the project discussions, so you’ll have a chance to begin building a new relationship, starting with an email introduction.

The 2021 LinkedIn Global State of Sales Report, which surveyed 7,500 B2B buyers and sellers in 11 countries, advises sellers to stay current with intel about project decision-makers and stakeholders. The survey found that 25% of decision-makers either change roles or leave the company in a given year. The survey also found that unfortunately, 85% of sellers reported that they lost at least one sales deal, or that a deal was delayed, because a key stakeholder left his/ her job. Of the many advantages acquired by tactfully remaining in touch with the primary decision-maker and influential stakeholders of every potential sales deal is receiving updates regarding who’s on and who’s off the team.

The Work From Home factor

Some companies have at least temporarily continued the work from home protocol for their employees when possible, but many have begun asking staff to work on-site at least 2 – 3 days/week. Still, the practice throws cold water on face2face sales meetings. The 2021 State of Sales Report indicates that B2B virtual selling gives the advantage to buyers, however McKinsey reports that 76% of B2B buyers prefer in-person sales meetings, or at least a telephone meeting. when evaluating a product or service that they’ve not used before. Zoom is convenient but apparently not considered ideal for first time meetings.

When appropriate, McKinsey found that 46% of B2B buyers say they’ll make purchases online online, but only 10% do so. Notably, 46% of B2B buyers feel it’s too difficult to compare the available products online. These buyers also are dissatisfied by the frequently slow responses to their inquiries.

The Digital transformation factor

Warning: 70% of digital transformation initiatives fall short of expectations. McKinsey reported that companies achieve the best results when a combination of human and digital interactions create a hybrid buyer’s journey. Because prospective buyers appreciate fast answers to their basic questions about your products and services, installing a chat bot and adding a FAQ tab to your website will expedite the delivery of information and facilitate a satisfying buyer’s journey that instills trust in your company and its solutions.

If you are tech savvy, explore and evaluate UX (user experience) and UI (user interface) digital tools. The free Adobe XD starter plan lets you design digital features that maximize the impact of touch points along the buyer’s journey, after-sale service experience and other customer service experiences that you’d like to enhance. Think carefully about how much digital interaction your prospects and clients will appreciate and strike a balance between digital and human communication.

Thanks for reading,

Kim

Image: Commodities traders at the Chicago Mercantile Exchange (founded in 1874)